

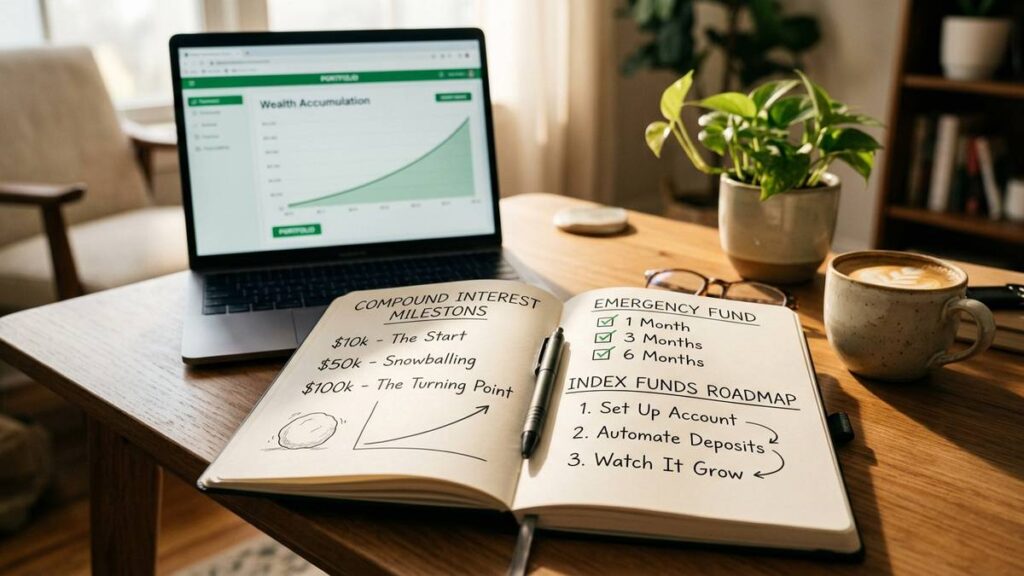
The Myth of the Silver Spoon
In our modern culture, the concept of wealth has become profoundly distorted by glamorous social media spectacles, overnight cryptocurrency millionaires, and inherited trust-fund dynasties.
When average working people with normal salaries look at high-net-worth individuals, they frequently assume that building serious financial freedom requires either winning the biological lottery (being born into affluent privilege) or winning the financial lottery (launching a billion-dollar technology startup or striking lucky on a speculative stock bet).
If you do not possess an inheritance and work a normal job with normal compensation, the culture subtly implies that financial abundance is completely out of reach.
That defeatist assumption is mathematically, historically, and demonstrably false.
Extensive empirical research into millionaire demographics (pioneered by studies like The Millionaire Next Door) reveals a striking truth: **over eighty percent of modern millionaires are first-generation affluent**.
They did not inherit fortunes. They were not corporate titans or celebrity athletes. They were teachers, accountants, electricians, nurses, small business operators, and middle managers who mastered the quiet, compounding mathematics of wealth building.
Building wealth from absolute scratch is not a mysterious art reserved for Wall Street elites; it is a systematic, mechanical discipline that anyone can learn and execute.
In this comprehensive instructional financial guide, we will dismantle the psychological traps that keep people trapped in the paycheck-to-paycheck cycle, break down the foundational math of compound interest, and provide a clear, step-by-step roadmap to take you from zero net worth to lasting, multi-generational financial freedom.
Step 1: Shift Your Identity from Consumer to Asset Owner
The fundamental divergence between people who remain financially stressed and people who build enduring wealth is not their income; it is their relationship with capital.
The Consumer Mindset: When a consumer receives money (a salary raise, a tax refund, an annual bonus), their immediate cognitive impulse is: ‘What can I buy with this money?’ They purchase depreciating liabilities: newer automobiles with expensive monthly loan payments, designer wardrobes, luxury vacations, and high-end consumer electronics. They convert hard-earned dollars into things that lose eighty percent of their value within three years.
The Asset Owner Mindset: When a wealth builder receives money, their immediate cognitive question is: ‘How many income-generating financial soldiers can I recruit with this capital?’
They view dollars as productive workers. Every dollar invested in an index fund, a rental property, or a profitable business asset goes out into the global economy, works twenty-four hours a day, earns dividends, and brings back more dollars.
Wealth is not measured by the luxury car you drive or the expensive watch on your wrist. Wealth is the silent, invisible accumulation of income-producing assets that pay you while you sleep.
Step 2: The High-Yield Emergency Fortress (Safety First)
You cannot build an enduring skyscraper on a foundation of loose sand. Before you invest a single dollar in the stock market, you must insulate your household against financial catastrophe.
Without an emergency fund, the first unexpected disruption in your life (a transmission failure on your car, a sudden medical emergency, a leaky roof) forces you to reach for high-interest credit cards, plunging you into the toxic quicksand of consumer debt.
Build a **$2,000 Starter Emergency Fund** immediately. Sell unused items around your house, take on temporary freelance overtime, and deposit that cash into an FDIC-insured High-Yield Savings Account (HYSA) paying four to five percent annual interest.
Once your high-interest debt is eliminated, expand that cash reserve into a robust **Three to Six-Month Living Expense Fortress**. Knowing that you can survive half a year of total unemployment without borrowing a penny gives you profound psychological peace and unshakable bargaining power in your career.
Step 3: The Debt Avalanche: Destroying High-Interest Consumer Debt
Carrying credit card balances charging twenty to twenty-eight percent annual interest is a financial emergency of the highest order. At twenty-four percent interest, your debt doubles every three years.
You cannot out-invest a twenty-four percent interest anchor with an eight percent stock market return.
Deploy the **Debt Avalanche Protocol**:
List all your non-mortgage debts from highest interest rate to lowest interest rate.
Pay the statutory minimum payments on all accounts to protect your credit score.
Attack the single highest-interest debt with relentless financial aggression, throwing every surplus dollar at it until the balance is exactly zero.
Once eliminated, roll that entire monthly payment into the next highest-interest debt. As balances fall, your payment momentum explodes like an avalanche, freeing up hundreds of dollars in monthly cash flow.
Step 4: The 100-Year Wealth Engine (Low-Cost Index Funds)
Once you are debt-free with an emergency fund, you activate the most potent wealth-building engine in human history: **automated, low-cost broad-market index fund investing**.
You do not need to read stock charts, time market swings, or guess which individual tech company will succeed next decade. Trying to pick individual winning stocks is an expensive fool’s game that even Wall Street hedge funds fail at ninety percent of the time.
Instead, buy the entire economy through total stock market index funds (such as Vanguard Total Stock Market VTSAX/VTI or S&P 500 VOO/VFIAX). When you invest in a broad market index fund, you instantly own a microscopic fractional share of the five hundred largest, most profitable, and most innovative corporations on planet Earth.
The Compounding Mathematics: If you invest just 400everymonthintoanS&P500indexfundstartingatagetwenty-five,assumingthehistoricalaverageannualreturnoftenpercent,yourportfoliowillcompoundintoover**1.3 million by age sixty**, despite you having contributed only $168,000 of your own money. The remaining $1.1 million is pure compound interest created by the productivity of the global economy.
Step 5: The Hierarchy of Investment Containers
To maximize your investment returns, feed your dollars through the proper tax-advantaged accounts in sequential order:
- Employer 401(k) Match: Always contribute enough to capture your full company match. A dollar-for-dollar employer match is an immediate, guaranteed one hundred percent return on investment that you should never leave on the table.
- Health Savings Account (HSA): If eligible, maximize your HSA for its triple-tax advantage.
- Roth IRA: Maximize your annual Roth IRA contribution. Money invested in a Roth IRA grows completely tax-free and can be withdrawn completely tax-free in retirement.
- Maximize Remaining 401(k) Capacity: Funnel additional savings back into your workplace retirement plan to reduce taxable income.
- Taxable Brokerage Account: Once tax-advantaged containers are filled, invest surplus capital in a standard brokerage account for flexible, long-term wealth building.
Lifestyle Creep, Multiple Income Streams, and Generational Wisdom
A foundational skill in long-term wealth preservation is learning to insulate yourself from lifestyle creep as your income naturally grows.
When ambitious professionals earn a promotion or land a higher-paying client, their immediate human tendency is to upgrade their baseline lifestyle to match their new earnings: renting a more expensive luxury apartment, dining at high-end restaurants three nights a week, or financing a luxury vehicle.
This phenomenon keeps high-income earners living in quiet financial desperation. Someone earning two hundred thousand dollars a year who spends two hundred and five thousand is fundamentally broker than someone earning sixty thousand dollars who invests fifteen thousand.
Adopt the ‘Fifty Percent Raise Rule’: whenever you receive a raise, bonus, or unexpected financial windfall, allocate fifty percent to celebrating your hard work (a weekend getaway or special dinner), and immediately funnel the remaining fifty percent into automated investments. This allows you to enjoy life today while accelerating your timeline to financial independence.
To ensure your wealth-building strategy stands strong across economic cycles, cultivate multiple independent streams of supplementary income. Funneling an extra five hundred to one thousand dollars each month directly into your automated index fund investments cuts your timeline to financial independence in half.
Finally, teach your financial principles to the people you love. Building wealth is not a solitary competition; it is a shared family journey toward generational stability. Talk openly with your children about the difference between assets and liabilities, how compound interest works, and the value of patient delayed gratification.
The Relationship Between Wealth and True Generosity
One of the most profound revelations experienced by long-term wealth builders is that money is ultimately a magnifying glass for your existing character.
If you are greedy and fearful with five hundred dollars, you will be greedy and fearful with five million. But if you cultivate habits of gratitude, empathy, and generosity while building wealth from scratch, capital becomes a powerful vehicle for good.
Allocate a regular percentage of your monthly income to causes and organizations that align with your deepest values. Generosity breaks the toxic grip of financial anxiety, reminding you that true wealth is not merely what you accumulate, but what you are able to joyfully share with the world.
Take your first step today with confidence, patience, and clear vision. Your future financial freedom is built on the quiet, faithful choices you make right now.
Financial peace is not about having everything; it is about having enough and knowing that you are completely in control of your financial destiny. Build your wealth with patience, protect it with wisdom, and use it to author a meaningful life.
Conclusion: The Quiet Journey to True Freedom
Building wealth from scratch is not flashy, dramatic, or fast. It is a quiet, steady, and remarkably peaceful discipline.
It is living on less than you earn, investing the difference automatically every month, and letting the compounding mathematics of time do the heavy lifting.
True wealth is not about impressing strangers with status symbols. True wealth is waking up on a Tuesday morning and realizing that your time belongs entirely to you.
Start today. Open your high-yield savings account, automate your first fifty-dollar transfer, and take the first courageous step on your journey to lifelong financial freedom.